Founders · 14 July 2026 · 9 min read
What UK Founders Get Wrong About Raising Funding
I've sat on the team side of funding rounds and watched good companies stall for avoidable reasons. Here is what separates the founders who close from the ones who keep pitching.
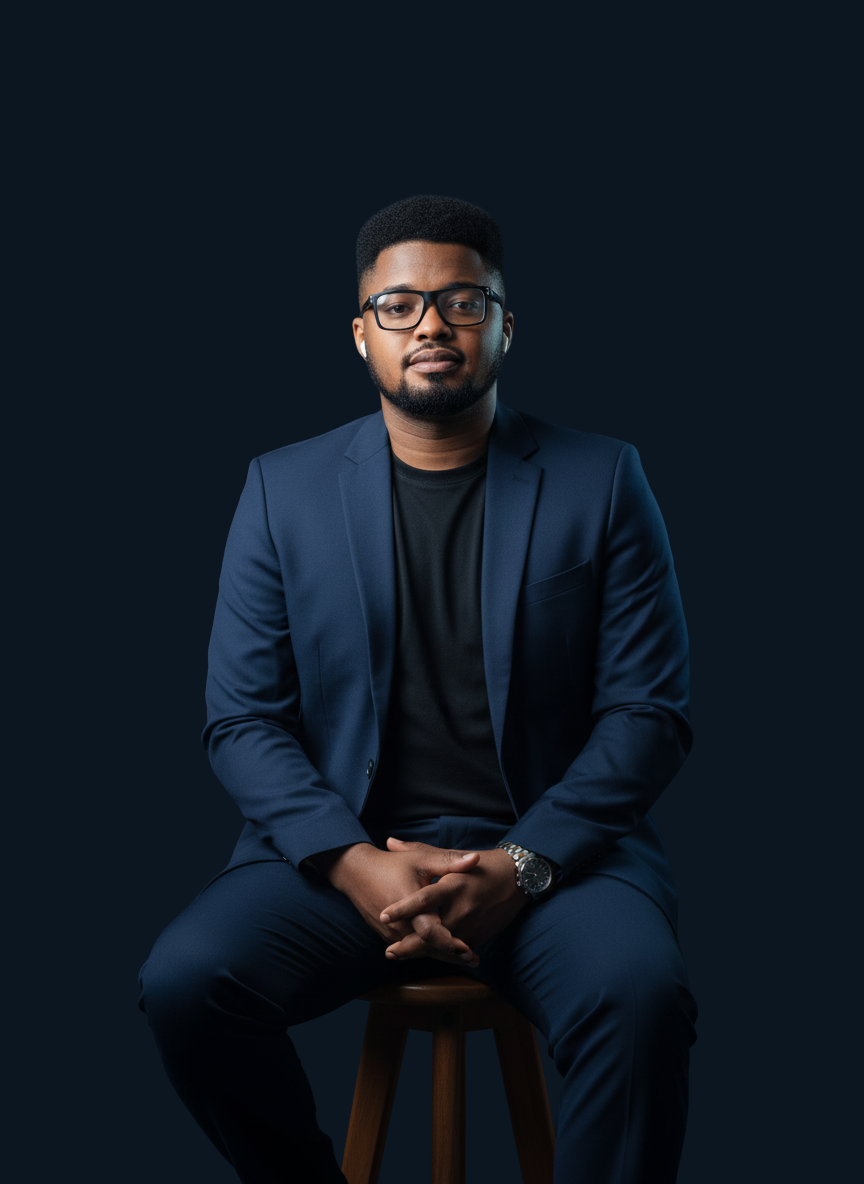
Princely Samuel O.
Founder, The Legacy Bench · Keynote speaker, Manchester UK
I have been part of teams during live funding processes — inside the data room, inside the awkward second meeting, inside the week where the lead goes quiet. From that seat, the pattern is unmistakable. Rounds rarely fail because the idea is weak. They fail because the founder is answering a different question from the one the investor is actually asking.
Mistake one: pitching the product instead of the machine
Founders love their product, so they spend forty minutes on features. Investors are not buying the product; they are buying the machine that produces customers, retains them and does it more efficiently over time.
Rebuild the deck around that machine: where demand comes from, what it costs to convert, what happens after someone buys, and what breaks first if you triple the input. If you can describe your business as a repeatable system with known constraints, you sound fundable even before the numbers are impressive.
Mistake two: treating traction as a number instead of a story
A revenue figure with no narrative is just a number that can be interrogated. A revenue figure with a narrative — this channel, this customer type, this conversion improvement after this specific change — is evidence of judgement.
Investors are underwriting your decision-making over the next five years. Every metric you present should quietly demonstrate that you know why it moved.
Mistake three: raising too late, from a position of need
The worst time to start a raise is when you have four months of runway. Desperation is legible in a room, and it changes the terms you are offered.
Start relationship-building nine to twelve months before you need capital. Send short quarterly updates to investors who passed. When you do open a round, you are not introducing yourself — you are confirming a trend they have already been watching.
- Month 1–3: build the list, get warm intros, share progress with no ask.
- Month 4–9: quarterly updates showing a consistent line going up and to the right.
- Month 10+: open the round with momentum, not with an emergency.
Mistake four: a founding team with no visible division of labour
When two co-founders both answer every question, investors hear duplication and unresolved authority. Clear ownership — who owns product, who owns revenue, who owns capital and risk — signals a company that can make decisions at speed.
This is also the most common reason a promising round quietly dies after the second meeting. Nobody says it out loud; they simply stop replying.
Mistake five: ignoring the unglamorous side of readiness
Cap table hygiene, clean contracts, IP assignment, a set of numbers that reconcile, and a data room that does not take three weeks to assemble. None of it wins you a round, but all of it can lose you one during diligence.
I have watched a term sheet slip because a former contributor held ambiguous equity from four years earlier. Fix that class of problem while it is cheap and boring to fix.
The mindset shift
Funding is not validation. It is fuel with an obligation attached. Some of the strongest businesses I have advised should never have raised at all — they should have priced properly, sold harder, and kept ownership.
Before you raise, answer honestly: does capital remove my real constraint, or am I hoping it will substitute for a decision I have been avoiding?
The takeaway
Investors back systems and judgement, not enthusiasm. Get investor-ready long before you are investor-hungry.